Satisfaction with Canada’s Big Five banks is slipping.
J.D. Power’s 2025 Canadian retail banking study found satisfaction with Toronto-Dominion (TD), Canadian Imperial Bank of Commerce (CIBC), Bank of Montreal (BMO), Royal Bank of Canada (RBC) and Scotiabank fell seven points, while satisfaction with midsize banks rose five points. High fees, poor service and competing offers are the main reasons why people switched their main financial institution, according to the same study.
If you’ve been considering switching out of your current bank, you have more options than you think: credit unions or CU. If you’re not sure what that is or if you need a breakdown of every option, we got you.
BECOME A GREEN LINE MEMBER TODAY
What’s a credit union?
Credit unions are regulated non-profit co-operatives and member-owned financial institutions.
Each member can vote on decisions and even run for a board position. Credit unions are committed to “understanding members’ needs and providing personalized financial advice to help them achieve their goals,” according to the Canadian Credit Union Association (CCUA).
Members don’t just have a say in how the institution is run. Profits are also reinvested in the credit union or the communities it serves.
Whether you want a financial institution that speaks your language, are interested in one of Toronto’s cultural or community-based credit unions, or want to bank with an institution whose values better align with your own — including where and how your money is invested — a credit union may appeal to you.
To save you from sifting through all the information about every credit union available in Toronto, I evaluated each institution using two questions:
- Could a Toronto household reasonably use the credit union as its main alternative to a mainstream bank, based on branch access, scale, digital banking and product breadth?
- How much value does it deliver through rates, fees, transparency and everyday usability?
Read on to find the answers.
Meridian
Winning best branch access in Toronto and ranking among the credit unions with the lowest Non-sufficient funds (NSF) fees at $10, Meridian is a clear winner in the best overall category.
Meridian is Ontario’s largest credit union, with approximately 360,000 members, $27.3 billion in assets and a one-time membership “fee” of just $1, which actually buys you a share in the institution.
Beyond banking, in 2025 Meridian invested $3.3 million back into the community in areas such as financial literacy, support for housing and climate organizations and 4,663 volunteer hours.
Best for: A Toronto household that wants the closest all-in-one replacement for a Big Five bank, with branches, digital banking, lending, investing and business services under one relationship.
What holds it back: Low ordinary savings rates and chequing fees that require minimum balances to waive them.
Fees and rates
- One-time membership deposit of $1
- High Interest Savings Account (HISA): 0.85%
- Tiered monthly fees range from $3 to $19 for chequing accounts, with no monthly plan fees for savings accounts
- Most of its specialty accounts are also no-fee, except for its seniors account
- Overdraft fee: $5 + 21% interest
- Minimum monthly balance (MMB) needed to waive the monthly fee ranges from $2,000 to $5,000
- Wire transfer fees for those sending money abroad can range from $30 to $120, depending on the amount
- $0 if you go over your credit limit on your credit card, although a transaction can still be declined and interest continues to apply
Products and services
- Everyday banking: Chequing, savings and U.S. dollar chequing accounts
- Specialty accounts: Options for students, Indigenous Peoples, seniors, newcomers and youth
- Registered accounts: TFSAs, FHSAs, RRSPs, RESPs, RDSPs and RRIFs
- Credit cards:
- cash back cards with annual fees ranging from $0 to $99
- travel rewards cards, with annual fees ranging from $49 to $99
- and a U.S. dollar option with a $65 USD annual fee
- Lending: Personal loans, lines of credit and mortgages
- Mortgage options: Fixed, variable, high-ratio, Flex Line, construction, friends-and-family, self-employed and secondary-suite
- Wealth management: Personalized financial planning and ESG or responsible investing through Aviso Wealth
- Members can also invest in GICs, mutual funds, stocks, bonds and ETFs through Qtrade Direct Investing and Aviso Wealth
- As with most credit unions in Ontario, the Financial Services Regulatory Authority (FSRA) insures eligible deposits in a Meridian account
Accessibility
- 12 branches in Toronto and three Advice Centres, the latter of which are located in:
- Its online banking app lets you deposit cheques and supports most digital wallets. You can even apply for a mortgage and open some accounts online
- The only eligibility requirement is to live in Ontario and have a valid SIN (for some interest-earning accounts)
DUCA
With just six branches in Toronto, DUCA was originally the Dutch Canadian Toronto Credit Union, but is now open to all Ontario residents with a $1 membership share. DUCA had around 93,000 members as of 2025 and $7.2 billion in on-balance-sheet assets.
Beyond banking, DUCA is B Corp certified, a designation that recognizes businesses meeting high standards for social and environmental performance, transparency, and accountability.
DUCA has stated goals that include fighting poverty and addressing social challenges through innovation and fair financial inclusion.
It also has a registered charity, DUCA Impact Lab, a hub that explores solutions to inequities in the financial system. It also invites non-profits, charities, social enterprises, foundations and associations to apply for grants and sponsorships.
According to their 2025 reports, by the end of the year, DUCAs Escalator Loan program had refinanced nearly $1 million in predatory loans for more than 130 people, while DUCA’s impact entities had delivered more than $1.8 million in impact financing.
Best for: A Toronto household that wants a credible full-service bank replacement without giving up disciplined fee and rate value.
What holds it back: Half as many Toronto branches as Meridian, weak ordinary savings rates and a less developed newcomer proposition.
Fees and rates
- Membership fee: $1 one-time member share deposit
- Monthly chequing fees: $4 to $15, depending on the account
- Specialty accounts: No monthly fees for students, young adults and seniors (60+)
- U.S. dollar account: $5 monthly fee, waived with a minimum daily balance of $7,500
- Euro account: No monthly fee
- Rise Chequing interest rate: 2%, with a $9 monthly fee waived when maintaining a minimum balance of $2,000
- High Interest Savings Account (HISA) rate: 0.25%
- Non-sufficient funds (NSF) fee: $10
- Stop-payment fee: $20
- Overdraft protection: $2.50 plus 18% interest; 21% interest without protection
- Returned-item fee: $6
- Coin rolls: $0.50 per roll
- Outgoing wire transfer fees: $25 to $100, depending on the amount
- Interac e-Transfers: Transaction limits vary by account
- Daylight Chequing includes five e-Transfers
Products and services
- Everyday banking: Five bundled chequing and savings account options, including low-fee, high-interest and premium accounts
- Specialty accounts: Options for students, young adults and seniors (60+)
- Foreign currency accounts: U.S. dollar and euro accounts
- Savings and investments: HISAs, term deposits, cashable term deposits and GICs
- Registered accounts: TFSAs and RRSPs
- Investment services: Mutual funds and other securities through Aviso Wealth, plus self-directed investing through Qtrade
- Credit cards: Six Collabria Visa cards, including cash back, U.S. dollar, Classic, Gold and Infinite options
- Personal lending: Personal loans, lines of credit and student lines of credit
- Mortgages: Low-rate mortgages, second mortgages, co-op mortgages and home equity lines of credit (HELOCs)
- Wealth management: Retirement planning, tax-efficiency strategies and investment planning
- Insurance: Offered through CUMIS Insurance
- Eligible deposits insured by the Financial Services Regulatory Authority of Ontario (FSRA)
- Profit sharing: Distributed $519,101 to members through its Do More Profit-Sharing Program for 2025
Accessibility
- Toronto locations: Six branches
- Membership eligibility: Open to all Ontario residents
- Membership requirement: $1 member share deposit
- SIN requirement: A social insurance number is required to open a personal account, according to DUCA’s FAQ
- ATM access: THE EXCHANGE, Interac and AccuLink networks
- In-person services: Student lines of credit can be applied for in-branch
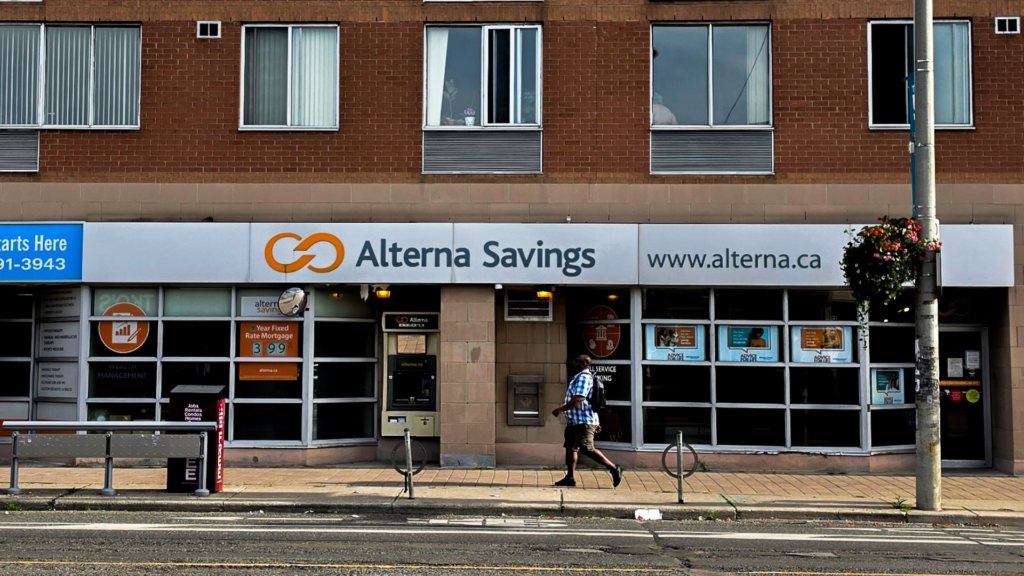
Alterna Savings
Alterna is the strongest full-service option for newcomers and community-focused banking.
It has seven branches across Toronto, an online chatbot, $13 billion in assets under administration and around 230,000 members, making it the second-largest CU in the city.
Alterna Savings recently merged with Tandia and also has a separate federally incorporated bank subsidiary.
If you care more than just meeting your day-to-day banking needs, Alterna says its Community Microfinance Program has operated for more than 25 years and supplied more than $10 million through 1,500-plus impact loans. It reports that 56% of the loans went to women entrepreneurs, 85% supported BIPOC entrepreneurs, the repayment rate remained between 95 and 98% and every $1 lent generated $4.37 in social and economic value. The program combines loans with financial education, credit-building, workshops and a microsavings component.
Best for: Newcomers, branch users and entrepreneurs who value community-focused financing.
What holds it back: a $50 NSF fee and weak ordinary savings rates.
Fees and rates
- Membership fee: $15 one-time member share deposit
- Monthly chequing fees: $0 to $14, depending on the account
- Pay-as-you-go chequing: No monthly plan fee; basic transactions start at $1.20 each
- ATM withdrawals (pay-as-you-go account): $2 per withdrawal
- U.S. dollar chequing account: No monthly fee; $2 per transaction
- Monthly savings fees: $0, although certain transactions incur additional fees
- Savings account interest rates: 0.05% to 0.35%, depending on the balance
- Nest Egg Term Deposit rates: 2.55% to 3.20%, depending on the term
- Non-sufficient funds (NSF) fee: $50
- Overdraft protection: $5 monthly or $5 per use, plus 19.99% interest
- Outgoing international wire transfer fees: $30 to $80, depending on the amount
- Newcomer benefits: Special rates on term deposits and mortgages through the New to Canada package
Products and services
- Everyday banking: Six chequing account options, including pay-as-you-go, low-, medium- and high-volume accounts.
- Specialty accounts: Options for students, seniors and newcomers
- Foreign currency accounts: U.S. dollar chequing account
- Savings: Regular savings accounts and Nest Egg Term Deposits
- Term deposits: Fixed-term, cashable and redeemable options.
- Registered accounts: TFSAs, FHSAs, RRSPs, RESPs, RDSPs and RRIFs
- Investments: Term deposits, investment shares, responsible investing through NEI and self-directed investing through Qtrade
- Wealth management: Financial planning and guided investment portfolios through Qtrade
- Credit cards: Six Collabria Visa cards, including two cash back, two low-rate and two travel cards (one in U.S. dollars)
- Personal lending: Personal, investment and outdoor adventure loans, plus digital loans through Fig
- Lines of credit: Personal, secured and student lines of credit
- Mortgages: Fixed-rate, variable-rate, reverse and investment mortgages
- Home, auto, creditor and travel insurance through Co-operators
- Deposit insurance: Eligible deposits insured by the FSRA
Accessibility
- Toronto locations: Seven branches
- Membership eligibility: Ontario residents
- Digital banking: Mobile cheque deposits, bill payments, account transfers, Interac e-Transfers and account alerts
- Digital wallets: Apple Pay, Google Wallet and Samsung Pay for credit cards
Parama
It’s a credit union with Lithuanian roots that is now open to the broader community. It reported $596.2 million in assets and more than 6,000 members in 2025. It has two branches, both in Toronto’s west end.
Best for: Rate-conscious west end residents who want no-monthly-fee everyday banking and competitive savings under one roof.
What holds it back: two Toronto branches, a $45 NSF fee and an incomplete overdraft disclosure.
Fees and rates
- Membership fee: $40 ownership share
- Monthly chequing fees: $0
- Minimum chequing balance: No minimum required
- Everyday Chequing interest rate: 0.25% on balances below $10,000; 0.50% on balances of $10,000 or more
- Daily Interest Premium Savings rate: 2.50%, with no promotional period or minimum balance
- Interac e-Transfers: Free outgoing transfers
- Everyday transactions: Unlimited deposits, withdrawals, cheque transactions and debit purchases at no additional charge
- Personal cheques: First 100 pre-printed cheques free
- Non-sufficient funds (NSF) fee: $45
- ATM withdrawals: Free at participating Canadian THE EXCHANGE ATMs; $1 at other Canadian ATMs
- Registered account transfer-out fee: $100
- Domestic wire transfers: $25 CAD
- International wire transfers: $35 CAD; $25 USD to the United States or $35 USD elsewhere
- Incoming wire transfers: $15 in the transfer currency
- Overdraft protection: Rates and fees not clearly disclosed
- Personal loan rates: Starting at 6.60%
- Personal line of credit rates: Starting at 8.10%
- Home equity line of credit (HELOC) rates: Starting at 4.85%
- Mortgage rates: Starting at 3.90% for owner-occupied properties
Products and services
- Everyday banking: Everyday Chequing and Daily Interest Premium Savings accounts
- Foreign currency accounts: U.S. dollar and euro savings accounts
- Savings and investments: Conventional, no-rebate, cashable, U.S. dollar and index-linked GICs
- Registered accounts: TFSAs, FHSAs, RRSPs, RESPs and RRIFs. No RDSP publicly listed
- Investment services: Mutual funds and other securities through Aviso Wealth
- Self-directed investing: Qtrade, including guided investment portfolios
- Credit cards: Collabria Visa credit cards
- Personal lending: Personal loans, RRSP loans, student loans and personal lines of credit
- Overdraft alternative: Personal line of credit linked directly to a chequing account
- Mortgages: Residential, commercial and co-op mortgages, bridge financing, refinancing and HELOCs
- Insurance: Loan, line-of-credit and mortgage insurance through CUMIS
Accessibility
- Toronto locations: Two branches.
- High Park North
- Kingsway South
- Online application requirements: SIN, one piece of valid government-issued photo ID, email address and mobile number registered in the applicant’s name
- In-person application requirements: SIN, two pieces of identification and proof of address
- ATM access: Participating Canadian THE EXCHANGE ATMs
- Digital banking on iOS and Android: Online banking and mobile app supporting bill payments, transfers and mobile cheque deposits
Luminus Financial
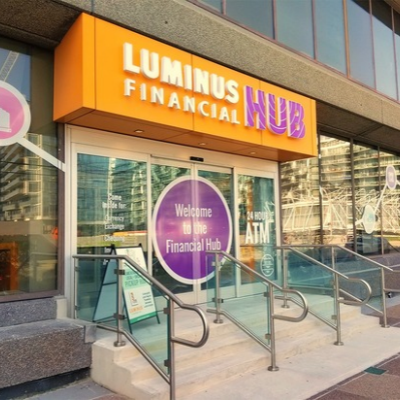
Luminus reported $281.7 million in assets in 2025 and has two Toronto branches.
Best for: Someone in the west end who can route payroll or pension to Infinite Chequing and prefers digital banking.
What holds it back: just two branches, mandatory annual dues, a 40% unauthorized-overdraft rate, a dormant-account fee and some gaps or inconsistencies in public disclosure.
Fees and rates
- Membership fee: $25 one-time ownership share
- Membership dues: $1.25 monthly (15 annually)
- Monthly chequing fees: $0 for Infinite Chequing; Classic Chequing is pay-per-use
- Classic Chequing transaction fees: $1 for most withdrawals, bill payments, debit purchases and transfers. Deposits are free
- Infinite Chequing: No monthly account fee, minimum balance or listed day-to-day transaction charges. Generally requires full payroll or pension deposits
- Classic Savings interest rate: 0.05%
- Infinite Savings interest rate: 1.50%
- TFSA interest rate: 1.50%
- Infinite Savings transaction fees: No deposit fees; $1 per withdrawal or transfer
- Non-sufficient funds (NSF) fee: $10
- Registered account transfer-out fee: $100
- Overdraft fee: $30 for exceeding an authorized overdraft
- Overdraft interest rates: 21% with authorized protection; 40% without authorization
- Missed loan payment or loan-related NSF fee: $50
- Incoming wire transfers: $15
- Outgoing wire transfers: $30
- Interac e-Transfers: Free incoming transfers; $1 per outgoing transfer
- Credit card annual fees: $0 to $120
- Credit card purchase interest rates: 12.99% to 20.99%
- Strike Loan: Fixed 8.99% interest rate over two years
- Mortgage application fees: Free for standard applications; up to 1% for certain co-op, co-ownership and equity-lending applications
Products and services
- Everyday banking: Classic Chequing and Infinite Chequing
- Foreign currency accounts: U.S. dollar account
- Savings accounts: Classic Savings and Infinite Savings
- Registered accounts: RRSPs, TFSAs, RESPs and RRIFs
- Investments: GICs and investment shares
- Credit cards: Six Collabria Visa cards
- Personal lending: Personal loans, lines of credit, consolidation loans and RRSP or investment loans
- Specialty lending: Strike Loan for eligible unionized workers, offering up to $5,025
- Mortgages: Conventional open and closed mortgages, high-ratio financing, refinancing and renewals
- Specialty mortgages: Co-op and co-ownership mortgages
- Ultimate Mortgage: Combines a mortgage with revolving credit
- Insurance: Offered through CUMIS and Co-operators
Accessibility
- Toronto locations: Two branches
- Weston
- Eringate-Centennial-West Deane
- Membership eligibility: Ontario residents
- Membership requirements: Two pieces of identification, a $25 ownership share and $1.25 in monthly membership dues
- ATM access: Free withdrawals at Luminus and participating THE EXCHANGE network ATMs
- Digital banking: Online account opening and mobile cheque deposits
A few others deserve an honourable mention:
- YNCU combines no-fee starter banking, a $10 NSF fee and strong financial-education and community programs, but has only two transitional Toronto branches
- FirstOntario offers the highest ongoing savings rate, 2.85%, through its Saven Financial division, with no minimum deposit, monthly fee or temporary promotion. However, Saven is a separate savings-only platform and FirstOntario has no conventional Toronto branch
- IC Savings offers six Toronto branches and no-fee everyday banking through its Perfetto account, but its 0.45% savings rate and incomplete public lending prices weaken its value
- WFCU offers an interest-bearing chequing account paying as much as 2%, but the qualifying account costs $15 a month, its NSF fee is $65 and it has only one Toronto branch
- Ukrainian Credit Union has four Toronto branches, open membership, community service and strong Ukrainian-newcomer support, but its $150 membership-share requirement, $48 NSF fee and transaction charges make it comparatively expensive
- BCU Financial offers unlimited no-monthly-fee chequing, newcomer support and competitive savings, but its single Toronto branch and narrower product portfolio limit its usefulness as a complete Big Five replacement
Do you have other questions about navigating banking and finance in Toronto? Let us know in the comments under the story.
Fact-Check Yourself
Sources and
further reading
Don’t take our word for it — check our sources for yourself.
Join the conversation